Julian Choo
Debt Consolidation
One repayment is all you need.
As a homeowner juggling other debts, you know that feeling too well.
Answer the questions below so we can help you roll your debts into your home loan, even if your bank said no 👇
Julian Choo Loan Market
Award-Winning Service
300+ 5-Star Google Reviews
Sound familiar?
Your pay lands. The repayments take it.
Each debt has its own rate, fee and due date, and the balances barely move. That isn't a character flaw. It's a structure problem, and structure can be changed.
Too many due dates
Several minimum repayments a month, and one slip puts the rest at risk.
Interest eating the repayment
At card and personal-loan rates, most of what you pay goes to interest instead of the balance.
Your bank already said no
That's one lender's policy. It isn't the whole market.
Something on your credit file
Late payments, defaults, ATO debt or hardship. Specialist lenders assess the full picture.
Before
After
Plus a plan to move you back to a mainstream rate.
Illustrative only. Rolling short-term debts into a home loan can lower what you pay each month, but over a longer term it can mean more interest overall, and the debt becomes secured against your home. Every plan we arrange includes a way to pay it down.
Planning before paperwork
How We Protect Your Credit Score
We review your full credit file, run the numbers and choose the right lender before any application goes in. You apply once, with the lender that fits, which keeps enquiries to a minimum and gives you the strongest shot at approval.
We start with your credit file
With your permission, we go through it line by line: every default, late payment and enquiry, when it was listed and when it drops off.
We find the right lender
What you owe, what you earn, your equity and your file, matched against each lender's policy. Nothing is submitted until one genuinely fits.
One well-aimed application
A cluster of recent enquiries makes lenders nervous. We aim for one application to one carefully chosen lender.
We stay with you after settlement
We review your situation regularly, and once your credit has recovered, we look at moving you to a mainstream lender with a sharper rate.
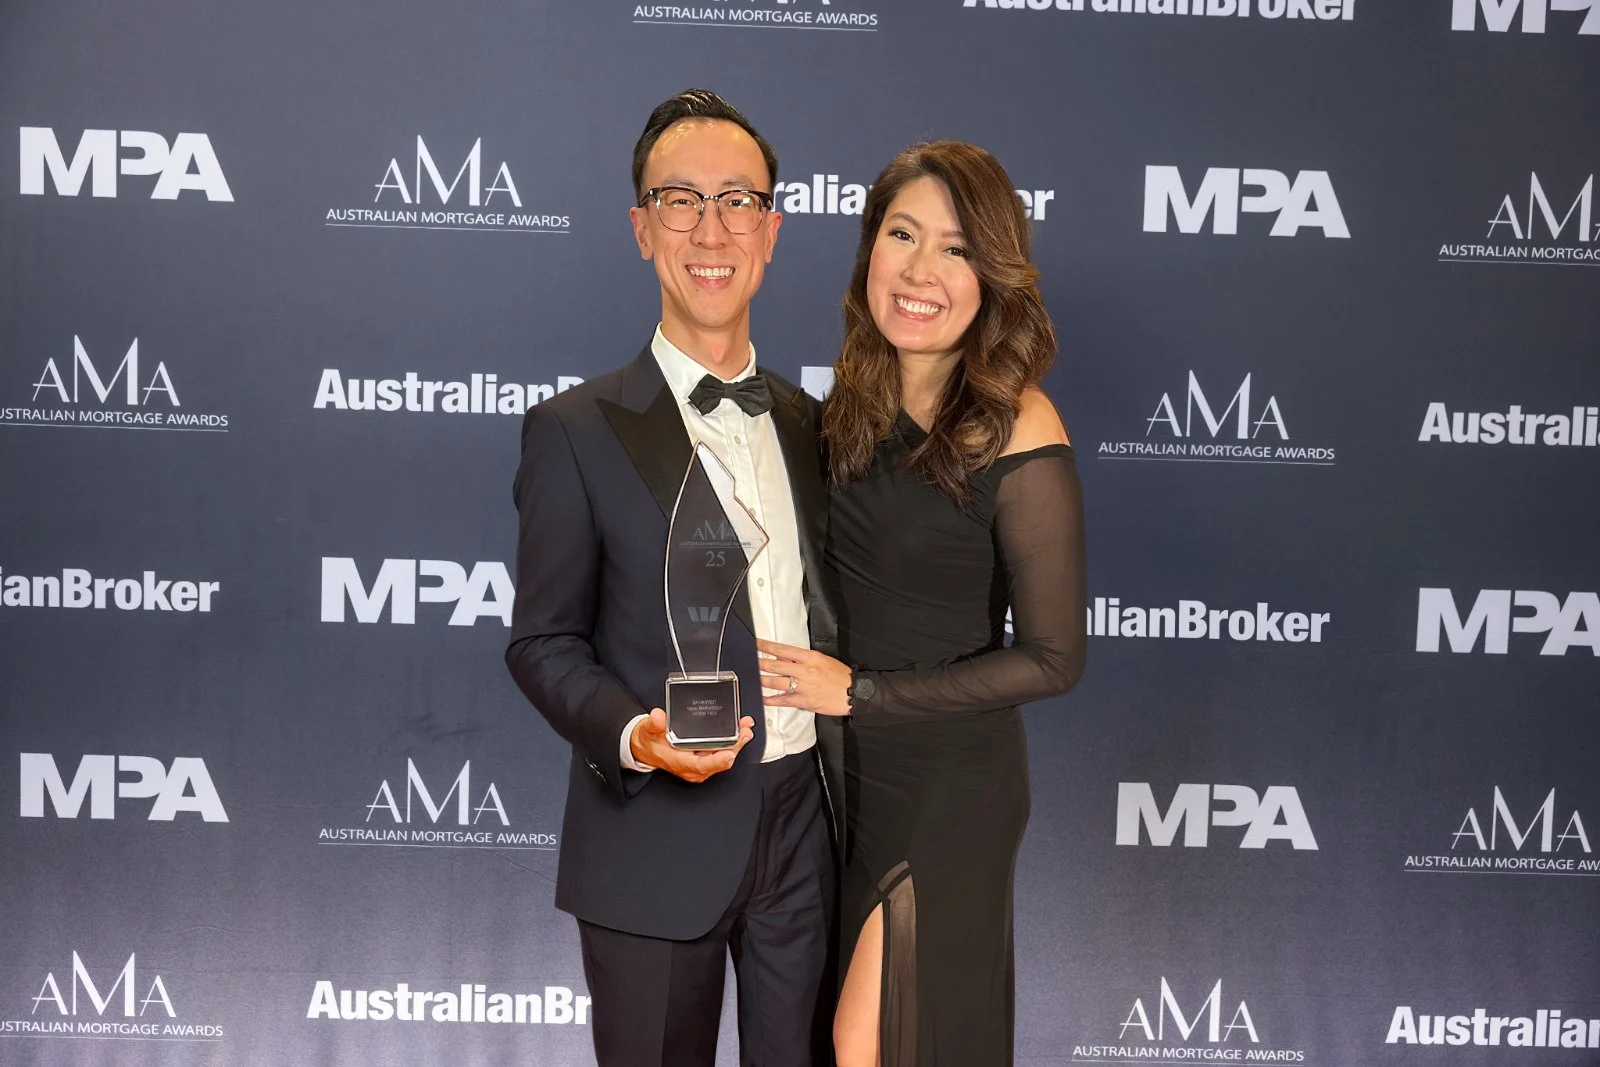
Your broker
Julian Choo
Award-winning mortgage broker · Loan Market · Australia-wide
My vision is to make financing as simple as possible for everyone. Inspired by my own mortgage broker who helped set up my family's finances for success.
As a Loan Market Mortgage Broker, I have the power to negotiate to get a loan that suits your needs. With access to 100+ banks and lenders and thousands of products, I'll make the lenders work hard for you.
Tricky files welcome. Defaults, late payments, ATO debt, self-employed income and previous declines.
Bound by Best Interests Duty. We only recommend a change that works in your favour.
Straight answers. If it doesn't stack up yet, you'll hear that, along with what would need to change first.
Don't Just Take Our Word For It
We had an excellent experience working with Julian Choo from Loan Market. From the very beginning, Julian was professional, knowledgeable, and incredibly supportive throughout the entire process. He was always available to answer our questions, kept us informed at every stage, and made what could have been a stressful process feel smooth and straightforward. His attention to detail, prompt communication, and dedication to finding the best outcome for us were truly outstanding. Julian went above and beyond to help secure our home loan approval, and his expertise and commitment gave us confidence every step of the way. We genuinely appreciated his honesty, patience, and willingness to help whenever needed. We highly recommend Julian Choo to anyone looking for a reliable, efficient, and trustworthy mortgage broker.
A wonderful smooth experience working with Julian and team. They were there every step of the way, always willing to help and answer any questions we had. Julian, was very professional, helpful and knowledgeable. He was very friendly, patient and took the time to explain everything in a very simple way . His knowledge and professionalism were outstanding, and he made sure we understood our options before making any decisions. We couldn't have asked for a better or easier experience and highly recommend anyone looking for a reliable and supportive broker.
I cannot recommend Julian Choo highly enough! We initially engaged with a different mortgage broker, but that experience left us feeling confused and overwhelmed. From the moment we connected with Julian, everything changed. His deep knowledge of the mortgage process, coupled with his exceptional customer service, made a world of difference. Julian took the time to explain every step clearly and answered all our questions with patience and expertise. What stood out the most was his incredibly fast turnaround — he kept everything moving smoothly and efficiently, which made our journey so much easier and less stressful. Thanks to Julian, what started as a daunting experience turned into an exciting and positive milestone. If you're looking for a mortgage broker who truly cares about his clients and delivers results, Julian is the one to trust!
Access 100+ lenders in one place
Straight answers
Frequently Asked Questions
I've already been knocked back by a bank or another broker. Is it still worth getting in touch?
Definitely. Plenty of the people we help have heard "no" at least once before they find us. A bank can only lend within its own rules, and some brokers stop looking after the first knockback. We have access to 100+ lenders, including specialists who work with things like patchy credit, ATO debt and missed repayments. They look at your whole story, not just one bad chapter, when they assess and price your loan. Fill the form above and we'll give you an honest answer about what's possible.
Will filling the form affect my credit score?
No. You're simply sharing a few details so we can understand where you're at. A formal credit assessment only happens down the track, if you decide to go ahead and apply with a lender we've matched you with. Until then, talking to us is free and your credit file stays exactly as it is.
Is this a Part IX debt agreement?
No. A Part IX debt agreement is a formal insolvency arrangement that's recorded on the National Personal Insolvency Index and your credit file, and it can limit your borrowing for years. What we arrange is a refinance: your existing debts are paid out and rolled into a properly structured home loan, so you're left with one repayment and no insolvency record.
Why not just go straight to my own bank?
Your bank can only say yes to loans that fit its own policy. If you don't tick every box, the answer is no, and a lot of homeowners take that as a no from everyone, which often isn't the case. As a Loan Market broker, we can compare 100+ lenders, including specialist lenders your bank is unlikely to mention. Put simply, a bank is there to sell its own loans. We're here to find the right loan for you, whichever lender it's with.
I'm self-employed. Is that going to be a problem?
Not at all. We help self-employed people all the time. Lenders will usually want slightly different paperwork, like your BAS, tax returns, notices of assessment or contracts, and some are far better than others at understanding self-employed income. We know which ones, so you're not stuck applying with lenders who were never going to say yes.
Isn't debt consolidation just shuffling my debt around?
If it's set up badly, it can be. A poorly structured consolidation simply stretches short-term debts out over the life of your home loan, so you pay them off far more slowly and often pay more interest overall. Done properly, it looks very different: one repayment instead of several, a clear plan to pay the debt down, and regular reviews to see whether you can move to a sharper rate as your credit and equity improve. It's the difference between buying time and actually getting ahead.
Will my repayments definitely go down?
Not always, and we'd rather be upfront about that. It depends on a few things: your loan size and term, the interest rate, your LVR (how much you owe compared with what your property is worth), whether lenders mortgage insurance applies, any refinancing costs and fees, and what a lender assesses you can afford. We'll run the numbers with you, and because we're legally required to act in your best interests (known as our Best Interests Duty), we'll only recommend a change that genuinely works in your favour.
Will this make me "debt-free"?
Not in the strict sense, and we try not to throw that phrase around lightly. Once the money in your offset account matches your loan balance, you're effectively paying no interest and you'd have enough to clear the loan if you wanted to. But the loan is still there, and the money in your offset is still yours to access. Think of it as a projected path to owning your home sooner, not a guarantee that you'll owe nothing by a particular date.
What does it cost to work with you?
For standard residential home loans, there's generally no fee for our service, as brokers are typically paid a commission by the lender. If a fee could apply to your situation, we'll let you know before you commit to anything. Other costs may still come up along the way, such as lender fees, valuation fees, government charges and the cost of refinancing away from your current loan.
Bank said no? Let's see what's actually possible.
60 seconds. No credit check. No obligation.
Julian Choo — Loan Market
© Loan Market | ABN 89 105 230 019 | Australian Credit Licence 390222. This page provides general information only and has been prepared without taking into account your objectives, financial situation or needs. Debt consolidation may reduce your monthly repayments but can increase the total interest you pay if debts are repaid over a longer term. Moving unsecured debts into a loan secured by your home increases the risk to your property if repayments can't be maintained. All applications are subject to lender assessment, eligibility criteria, fees and charges.
If you're experiencing financial hardship, the National Debt Helpline offers free, independent advice on 1800 007 007.